UK MGA Insurance Market Report 2026
UK MGAs wrote about £7.2bn of premium in 2025, up a fifth. Lloyd's, the FCA, the PRA and the capital behind MGAs spent the same year deciding how much of it to trust.
Market size, growth rates, regional dynamics, and product-line data showing how embedded insurance is reshaping distribution through 2034.

Embedded insurance refers to insurance coverage that is seamlessly integrated into the purchase flow of a product or service, rather than sold as a standalone policy.
These embedded insurance offerings are typically delivered at the point of need – when customers are already engaged in a digital transaction – making protection contextual, easy to understand, and frictionless to activate.
For customers, this model simplifies access to relevant insurance offerings; for distribution partners, it creates incremental revenue and deeper engagement; and for traditional insurers, it opens scalable access to new customer segments through digital distribution. As APIs, real-time data exchange, and automated underwriting mature, embedded insurance products are becoming a core mechanism for increasing insurance penetration and modernizing distribution strategies.
Consequently, the embedded model is no longer experimental – it is increasingly viewed as a foundational pillar of future insurance ecosystems, as highlighted across every major embedded insurance market report.
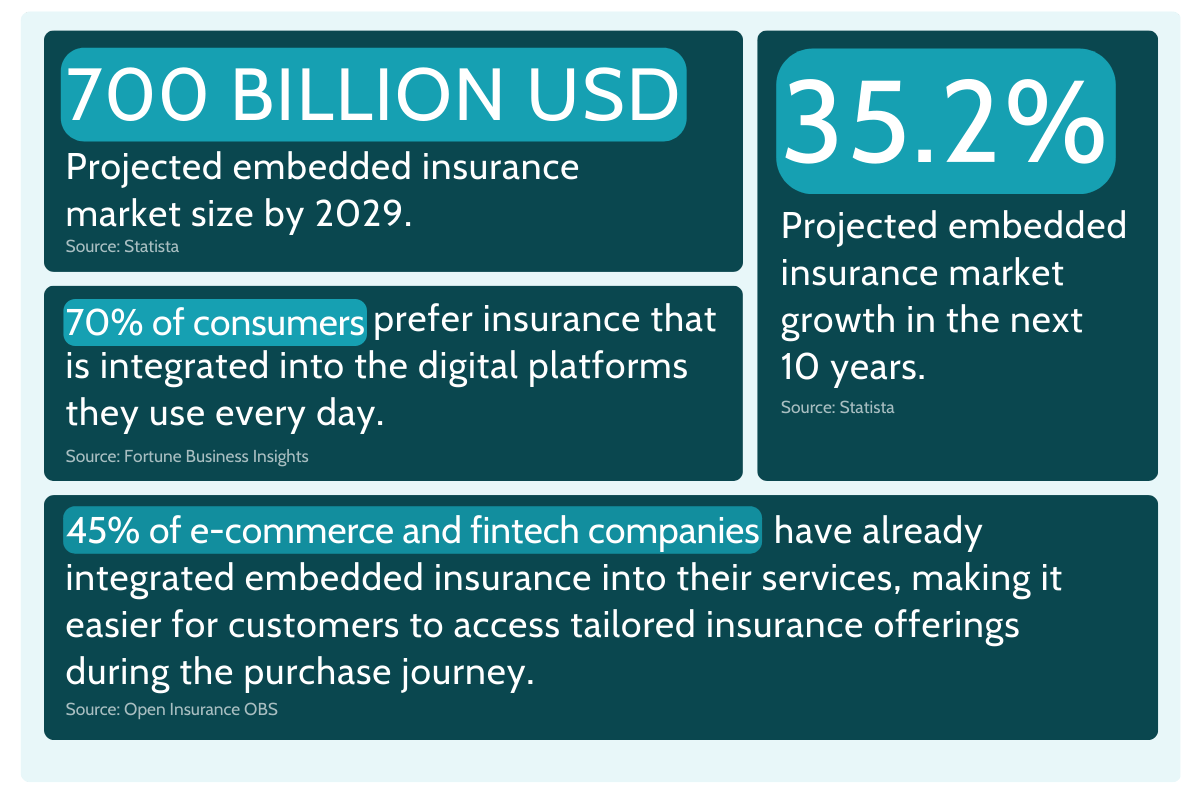
Key market indicators illustrate both the scale and velocity of this shift:
Following the broader market outlook, size and growth indicators reinforce the view that the embedded insurance market is not only expanding rapidly, but doing so at a pace that significantly outstrips the wider insurance industry. While traditional insurance channels continue to grow in low single digits in most mature markets, embedded distribution is scaling at multiples of that rate, driven by accelerating consumer demand for simple, contextual protection and by the growing ability of digital platforms to integrate insurance seamlessly into their core journeys.
From a revenue perspective, global embedded insurance revenues reached $56.98 billion in 2022 and are projected to rise to $161.60 billion by 2029, reflecting sustained momentum across both P&C and selected life insurance use cases.
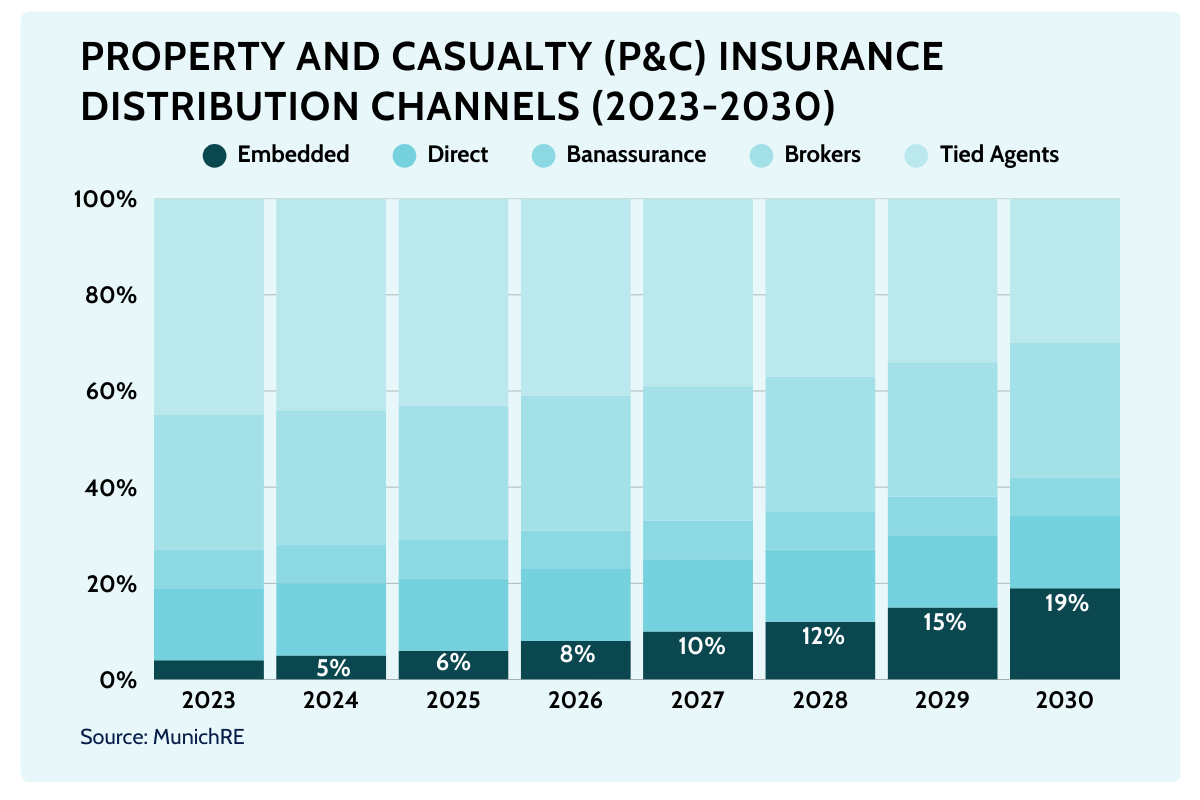
Alternative market sizing models, using a gross written premium lens, estimate the market at $213–355 billion in 2023, with forecasts converging toward approximately $1.1 trillion in GWP by 2033. While the range varies depending on definitions and product scope, every major embedded insurance report points to the same conclusion: embedded distribution is transitioning from a high-growth niche into a core insurance channel.
Shorter-term forecasts underscore this acceleration. The embedded insurance market is expected to grow from USD 18.09 billion in 2026 to USD 68.12 billion by 2030, representing a 30.37% CAGR as coverage migrates from stand-alone policies to "invisible" protection bundled into everyday digital experiences. This growth is being fueled by increasingly sophisticated embedded insurance solutions, including real-time underwriting, usage-based pricing, and modular coverage that aligns tightly with customer intent at the point of purchase.
Most notably, embedded distribution is on track to capture up to 15% of total insurance flows by the early 2030s, a shift unmatched by any other established insurance sales funnel. Compared with agents, brokers, bancassurance, or direct-to-consumer models, embedded insurance offerings represent the most dynamic growth vector in the market today – reshaping how insurers reach customers, how products are designed, and how value is created across the digital economy.
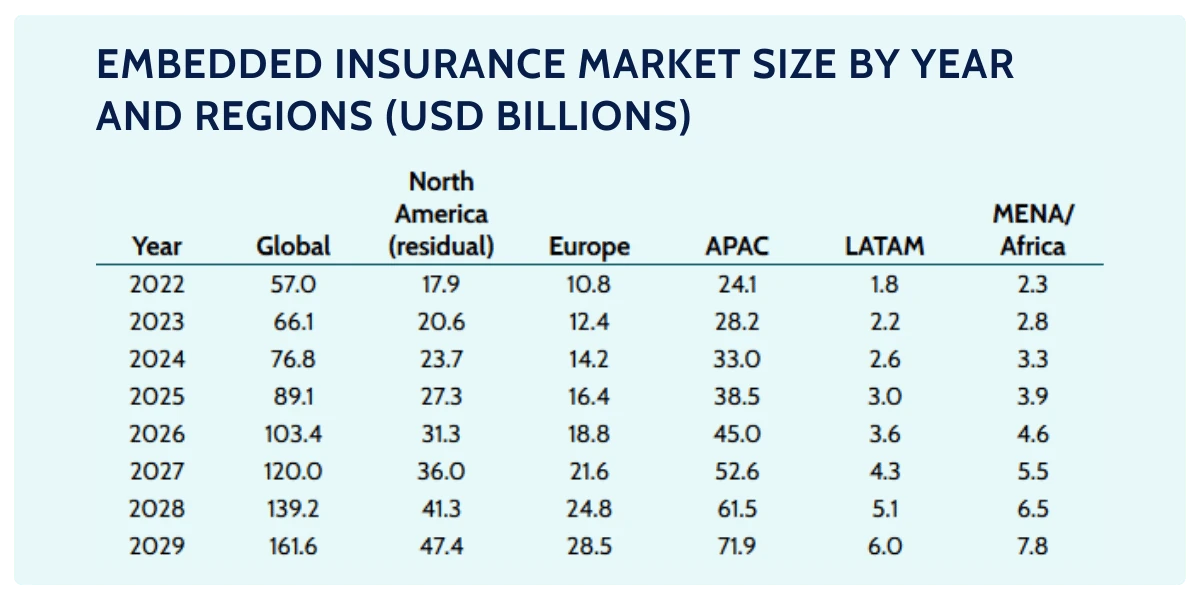
A regional breakdown of revenues further illustrates strategically important the growth of the embedded insurance market has become.
According to consolidated estimates from the latest embedded insurance market report, global embedded insurance revenues are projected to nearly triple from $57.0 billion in 2022 to $161.6 billion by 2029, but this expansion is being driven disproportionately by Asia-Pacific and other high-growth regions. APAC alone is expected to grow from $24.1 billion in 2022 to $71.9 billion by 2029, accounting for almost half of total global growth in absolute terms.
By contrast, North America and Europe show strong but more linear growth patterns.
North America's embedded insurance market size increases from $17.9 billion to $47.4 billion over the same period, while Europe grows from $10.8 billion to $28.5 billion, driven largely by retail, travel, and automotive use cases. However, the most striking relative momentum comes from emerging markets beyond APAC. LATAM and MENA/Africa, while smaller in absolute terms, more than triple their embedded insurance revenues between 2022 and 2029 – signaling that embedded distribution is often leapfrogging traditional insurance infrastructure entirely in these regions.
Taken together, the regional data underscores a key structural insight: the embedded insurance market is not expanding uniformly, but rather following digital adoption curves and platform density.
Published analyses consistently point to embedded insurance offerings absorbing volume from agency, bancassurance, and branch-led sales, rather than merely creating incremental demand.
In Asia, for example, McKinsey estimates that 66% of embedded insurance growth is driven by gross written premiums migrating out of traditional channels and into embedded distribution. This highlights a redistribution of value driven by superior timing, relevance, and customer engagement at the point of transaction.
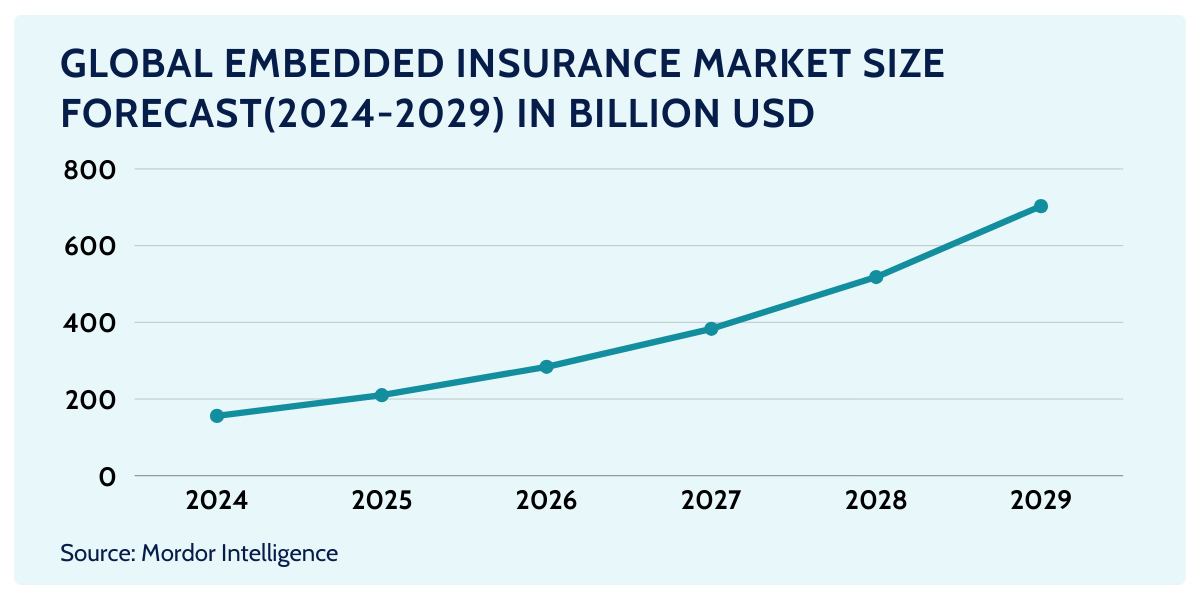
A broader global perspective reinforces this trend. According to the Swiss Re–Embedded Finance outlook, "EI 2.0" could account for roughly 16% of total global insurance distribution by 2032, equivalent to around $1.5 trillion in gross written premiums, assuming a total global market of approximately $7 trillion. In selected Property & Casualty segments, embedded distribution could approach 30% market share, taking volume primarily from tied agents and physical branch networks.
These estimates align with global market calibration data from International Association of Insurance Supervisors, which reported $1.75 trillion in gross reinsurance premiums in 2024, representing about 23% of total global premiums – implying a total global GWP base of roughly $7.6 trillion.
While P&C dominates today, embedded solutions are increasingly being explored for modular life insurance policies, credit-linked protection, and subscription-based coverage models.
As key companies across mobility, retail, and financial services deepen platform integration, embedded insurance is becoming a primary interface between insurers and end customers – reshaping how insurance is discovered, purchased, and perceived.
A closer look at product mix provides additional insight into how embedded insurance operates in practice.
In Europe, a representative market snapshot shows travel insurance accounting for 33.65% of the embedded insurance market in 2025, reflecting its natural fit with digital booking flows and high-intent purchase moments. Distribution is overwhelmingly digital: online platforms generate 93.10% of embedded insurance revenues, underscoring the central role of e-commerce platforms as the dominant access point for embedded insurance offerings.
Beyond travel, electronics protection and device insurance are consistently flagged as fast-growing lines, driven by rising consumer expectations around consumer protection, instant claims handling, and replacement services.
These products benefit from tight integration with checkout flows, pricing transparency, and immediate activation – features that traditional insurance channels struggle to replicate at scale.
Beyond channel disruption, the embedded insurance landscape is also defined by a rapidly evolving sector mix that reflects where seamless coverage delivers the most immediate value. Adoption is strongest in sectors where insurance can be tightly coupled with the core transaction, supported by real-time data, and delivered through online services with minimal customer friction.
Key embedded insurance placements and sector dynamics include:
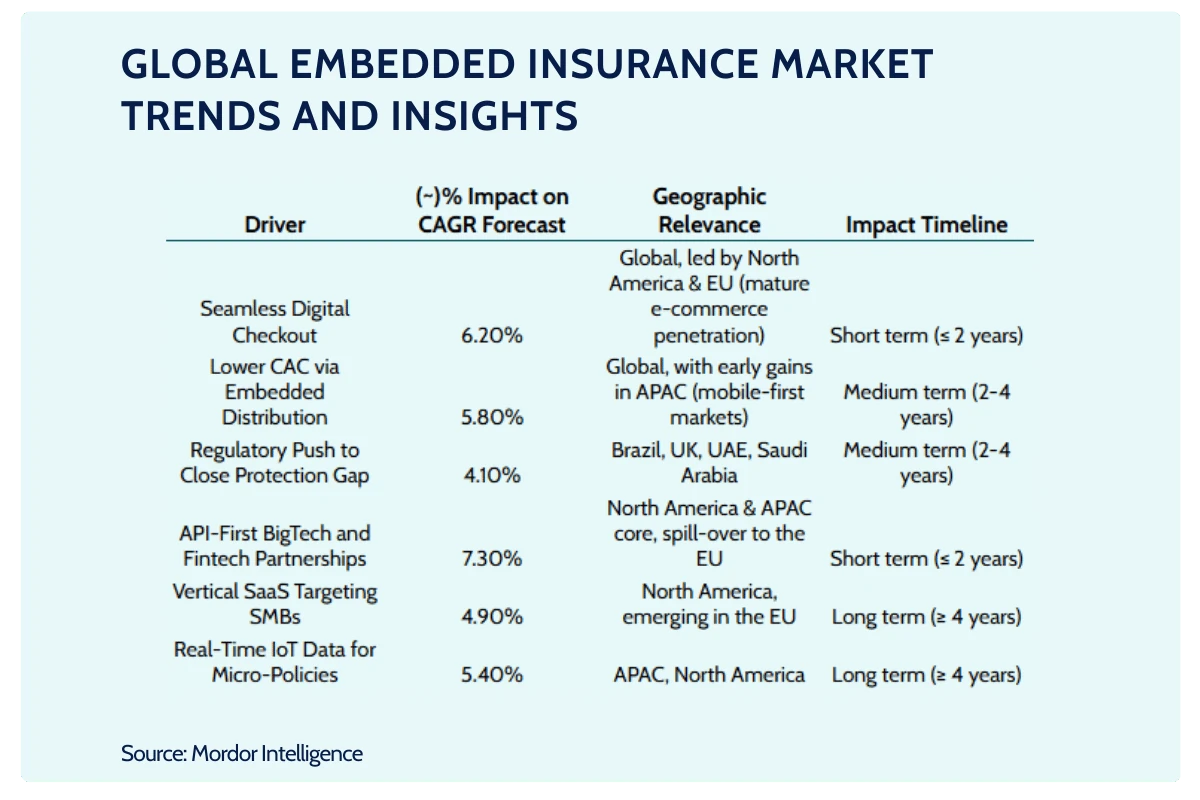
Across regions, the embedded insurance market is being shaped by a common set of structural trends that point to long-term maturation.
What is emerging is a more mature embedded insurance sector, defined by platform economics, modular technology, and deeper integration into everyday financial and digital experiences.
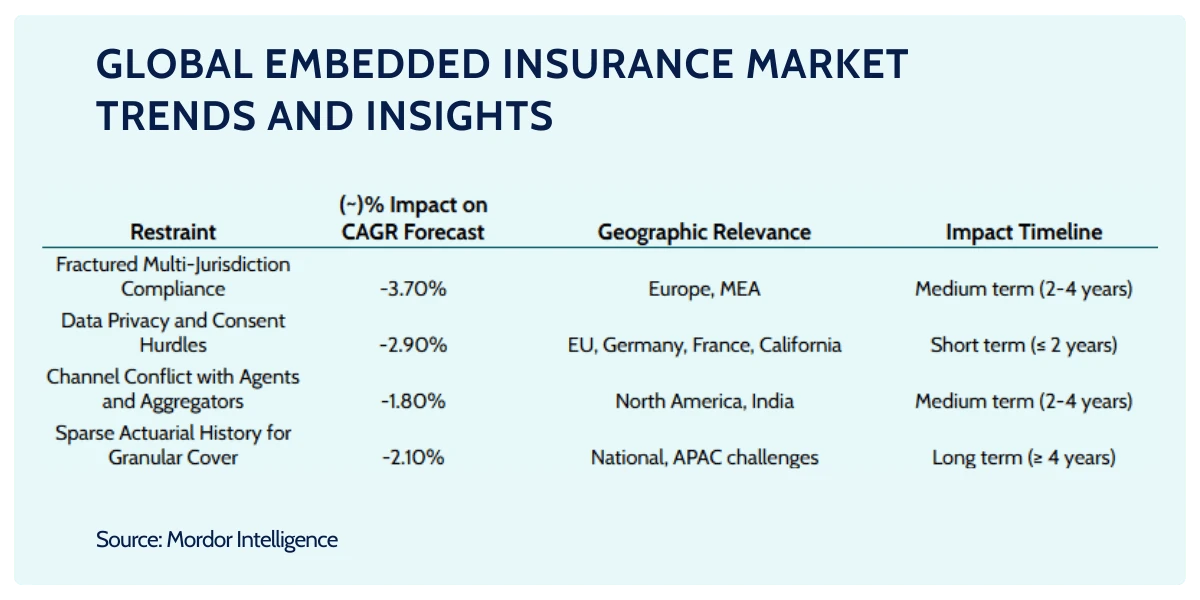
A defining shift is the rise of embedded insurance as "digital bancassurance 2.0."
Insurance is becoming a native feature inside banking/fintech journeys (accounts, cards, loans, wealth apps), not a separate "insurance tab" or referral. The bank/fintech becomes the distribution owner (and increasingly the UX owner), pushing insurers toward commoditization unless insurers differentiate through underwriting, claims, and service.
At the same time, API-first and modular productization are dramatically lowering integration cost and time-to-market.
Embedded insurance is shifting from bespoke integrations to modular building blocks: quote, bind, payment, policy issuance, endorsements, claims FNOL, document generation, cancellations – exposed as APIs/components that partners can plug into.
Finally, the market is evolving beyond simple add-on warranties toward higher-value lines such as auto, health, and SME insurance, as data availability and orchestration capabilities improve.
It's a shift from "checkout add-on" to "relationship insurance."
That pushes embedded models to prove they can handle the hard parts of insurance (claims, retention, regulation), not just distribution.
Read also: Top 5 Embedded Insurance Providers in 2026
AI is rapidly becoming a powerful accelerator of embedded insurance adoption.
By automating underwriting, pricing, claims triage, and fraud detection, AI enables embedded insurance solutions to operate in real time – making seamless insurance integration scalable.
How would that look like in practice?
An AI-enabled embedded insurance solution typically operates invisibly inside a digital journey. As a customer completes a transaction – such as purchasing a device, booking mobility, or onboarding with a financial platform – AI analyzes contextual signals in real time and instantly determines eligibility, risk, and pricing. The most relevant coverage is then surfaced as a natural part of the flow, with no separate forms or redirection, ensuring seamless insurance integration. Once accepted, the policy is issued automatically via APIs, and ongoing servicing or claims handling is largely AI-driven, using data inputs to validate events and resolve simple cases instantly.
For traditional insurers, AI lowers the barrier to participating in embedded models by reducing marginal costs and improving risk selection across high-volume, low-ticket products.
For financial institutions and platform operators, it enables more precise offers, smarter cross-sell logic, and better conversion without disrupting the core user experience.
As a result, embedded insurance is evolving into a highly efficient distribution channel, where coverage is context-aware, dynamically priced, and continuously optimized.
At the core of launching scalable embedded insurance products is the right technology foundation – and platforms like Openkoda are designed precisely for that purpose.
Openkoda is an insurtech development platform that enables insurers, fintechs, and digital partners to build custom embedded insurance solutions quickly and without vendor lock-in.
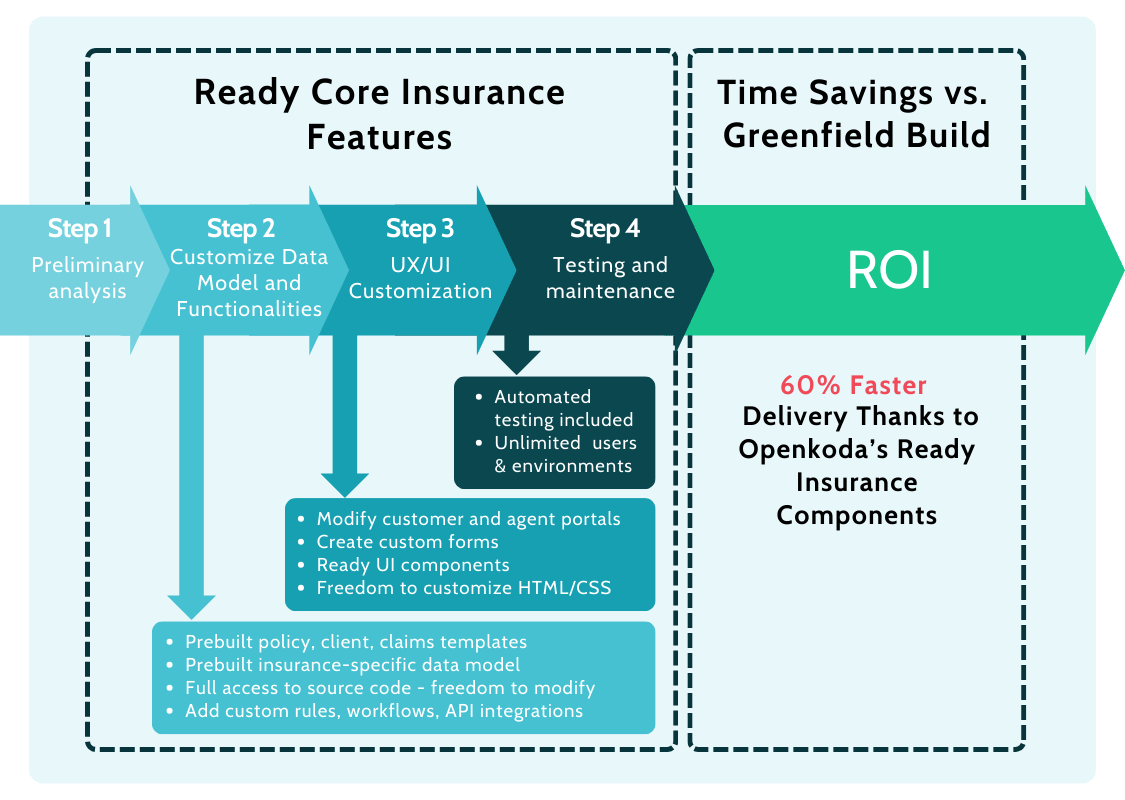
Its modular architecture and ready-to-use building blocks mean companies can design, test, and deploy embedded insurance offerings with seamless integration into websites, apps, or partner ecosystems in a fraction of the usual time.
By reducing development complexity and enabling flexible customization, Openkoda helps both traditional insurers and digital innovators respond to emerging demand and adopt cutting-edge technology without reinventing core systems.
Here's how designing an embedded insurance for device protection solution typically works with Openkoda:
UK MGAs wrote about £7.2bn of premium in 2025, up a fifth. Lloyd's, the FCA, the PRA and the capital behind MGAs spent the same year deciding how much of it to trust.
Surplus lines grew 10.4% in 2025 while filings outran premium in 2026. What specialty products ask of a PAS, and five tests to run before you buy one.
Six of the best policy management software systems for 2026, split by what they actually do: insurance policy administration, or internal policy governance.
Book a live, personalized demo with our product team - tell us your use case and see the platform work with your data. No commitment.