Guidewire Alternative: Openkoda vs. Guidewire for Policy Administration
How Openkoda, a highly customizable PAS with 12 ready modules, compares with Guidewire PolicyCenter on configuration, AI, deployment and ownership.
Five trends shaping insurance in 2026, from embedded cover and AI at scale to niche products, climate resilience and predictive risk management.

The US property and casualty industry has just had its strongest underwriting year in decades, which sets the backdrop for everything below.
AM Best put 2025 net underwriting income at $60.9 billion, close to triple the $22.1 billion the industry managed in 2024. Verisk and the APCIA, counting slightly differently, put it nearer $63 billion.
The combined ratio came in at 92.9% against 96.6% a year earlier, on a 6% rise in net earned premiums and a fall in incurred losses. Catastrophe losses took 7.6 points of that ratio, down from 8.8. Policyholders’ surplus passed $1.2 trillion.
US property and casualty underwriting income nearly tripled in 2025
Net underwriting income for the US property and casualty industry.
AM Best, Best's Special Report on 2025 US property/casualty results
Pricing has turned since. Commercial rates have been falling for several quarters now, though not in every line at once, which is what makes a record underwriting year an awkward thing to plan against.
A major challenge for the modern insurance industry is the protection gap: the difference between the cover that is needed and the cover actually bought.
On natural catastrophe risk alone, Swiss Re Institute measured that gap at $424 billion in 2025, up from $395 billion the year before. Its Natural Catastrophe Insurance Resilience Index reached about 27%, meaning roughly three quarters of global exposure is still uninsured. The spread matters more than the average: North America carries a $140 billion gap, while emerging Asia scores about 5%, so almost all newly accumulated exposure there is uncovered.
What does this imply?
For insurers, it represents a significant opportunity to expand their market and close the protection gap through innovative products and services. It also underscores the need for insurers to adapt and evolve to effectively reach underinsured customers and offer them appropriate coverage solutions.
Embedded insurance is rapidly becoming one of the most transformative trends in the insurance industry.
Published forecasts put it at around 15% of global gross written premiums by 2033, roughly $1.1 trillion, against 3% to 5% today. Treat the precision lightly: estimates for that year range from about $1.0 trillion to $1.2 trillion and none of them are observations yet.
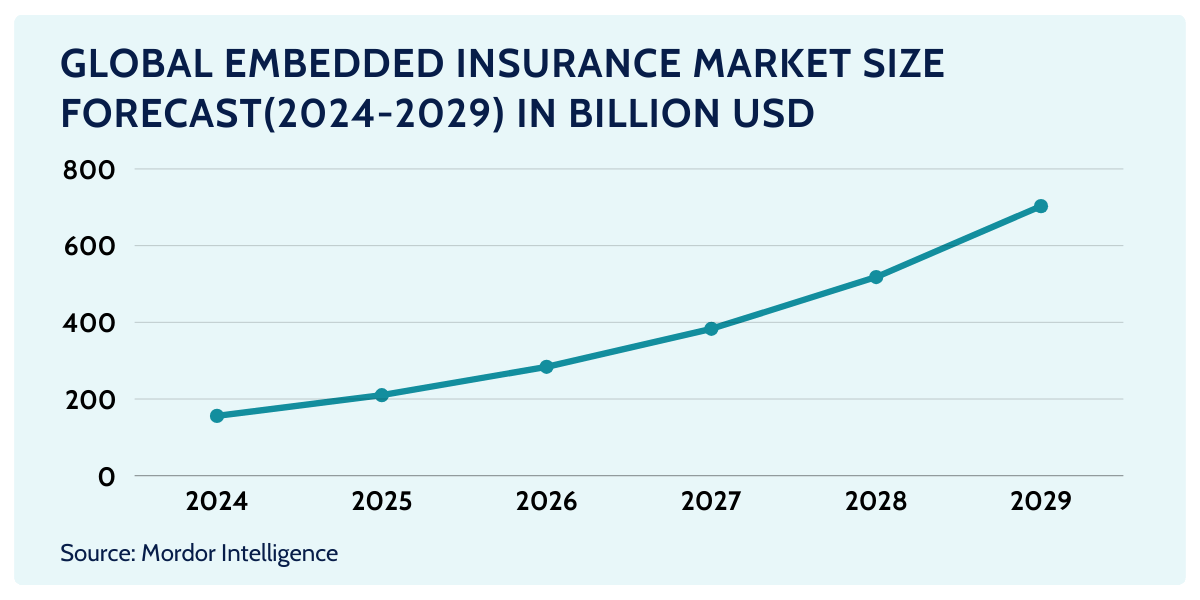
At its core, embedded insurance integrates coverage directly into the purchase process of products and services.
For example, imagine booking a vacation and being offered travel insurance as a simple, one-click add-on, or purchasing a high-end smartphone with device protection automatically included. That's the essence of embedding insurance products into the customer purchase journey.
Why is this approach a part of so many business strategies within the insurance industry?
For one, it tackles the common pain point of complexity in purchasing insurance.
Traditional insurance processes can be cumbersome, often requiring extensive paperwork, research, and decision-making.
In contrast, embedded insurance makes coverage easily accessible, offering it as a natural extension of an existing transaction.
The challenge lies in introducing it in a smart and efficient way.
That depends far less on the insurance product than on the integration around it.
The quote has to come back inside the partner’s own checkout rather than a redirect. The cover has to follow the underlying purchase when the booking moves or the order is refunded. And the journey has to carry the partner’s branding, because the customer believes they are buying from them, not from an insurer they have never heard of.
Programmes that get those three right tend to hold their conversion. The ones that bolt a form onto a checkout do not.
The AI revolution is here to stay, and many insurance leaders are exploring the best ways to integrate generative AI within their business processes - often with mixed results.
The challenge lies in determining where exactly AI can improve business efficiency without sacrificing the quality of provided services.
Adoption is no longer the question. Deployment at scale is.
Deloitte research puts 76% of insurance organizations as having deployed generative AI in at least one business function, with distribution, risk management and claims handling the busiest areas. Its 2026 Global Insurance Outlook frames the shift as moving from “what can AI do?” to “how do we make it work at scale?”
That is where the gap shows. 90% of insurance leaders say the way work gets done has to be reinvented for AI. About 25% have actually done anything about it.
So, where exactly can AI find its place in the software environment of an insurance company?
Let's explore a few examples.
One key area where AI is making a big impact in insurance is personalization.
By using real-time data from IoT devices - such as smart home sensors, wearable health trackers, or connected cars - insurers can now offer highly personalized policies that adapt to individual customer needs.
For instance, Tesla's IoT technology, as well as other auto insurers, allows it to adjust auto insurance premiums based on real-time driving behavior, rewarding safer drivers as well as offering usage based insurance. Similarly, John Hancock uses data from wearable health trackers to promote healthy lifestyles with rewards and personalized coverage.
AI helps analyze behavioral data, enabling insurers to tailor coverage and insurance premiums to each policyholder's unique lifestyle and risks enabling a complete data-driven insurance strategy.
AI-enabled insurance analytics are another significant advancement influencing your insurance business.
With AI-driven algorithms, your company can analyze large volumes of structured and unstructured data to detect patterns, predict risks, and process claims more efficiently.
For example, machine learning models can identify fraud signals during claims processing, helping insurers save millions on potentially fraudulent payouts.
There are also insurance software systems that can significantly speed up the report creation process.
Take Openkoda for example, which includes Reporting AI - a functionality that lets you generate complex SQL queries using nothing but natural language prompts. Just write what data you want to compare, and it will generate SQL code for you.
All this is done while only sharing the data types from the database schema - ensuring that sensitive information stays within your system.
To prepare for the AI era, it's essential for you to embrace data literacy and invest in understanding AI's applications in insurance.
You need to develop a solid grasp of how AI is transforming customer interactions, underwriting, claims management, and fraud detection to stay ahead of the curve.
It's also important to consider partnering with tech innovators to integrate AI solutions cleanly and keep up with the latest advancements.
Insurers are still building products for narrower and narrower groups.
As consumer needs evolve, insurance companies are focusing on niche products that address unique demands.
Here are three examples of such insurance product innovations just hitting the market:
Gig workers often face challenges securing coverage due to irregular income and work schedules.
To address this, insurers are creating on-the-spot coverage options, offering protection on a per-task or per-hour basis. This allows rideshare drivers or freelance couriers to access affordable insurance during work hours, without the burden of traditional policies.
The takeaway?
Per-usage products keep taking share, and the operational demands are different: cover that starts and stops, priced per task or per hour.
Mental health is becoming a central aspect of overall well-being, and insurers are responding by offering dedicated mental health coverage.
These policies cover therapy sessions, counseling, and digital mental health tools. By providing specialized coverage, insurers are making mental wellness more accessible while recognizing its growing importance. This shift not only helps individuals receive needed care but also reduces the stigma around mental health issues.
If your company specializes in healthcare insurance, this niche is worth watching.
As cyber threats grow more sophisticated, both individuals and businesses face increasing risks of digital attacks.
IBM’s 2025 Cost of a Data Breach Report put the global average at $4.44 million, down 9% year on year as faster containment brought the mean time to identify and contain a breach to 241 days, the lowest in nine years. The US went the other way: an all-time high of $10.22 million.
As an insurer, you can respond by offering cyber insurance products that protect against data breaches, ransomware, and other cybercrimes. These policies provide your clients with financial support in the event of an attack, along with resources for recovery and prevention.
Cyber cover is becoming a standing requirement rather than an option. The market itself is smaller and slower than the forecasts suggested: Swiss Re put global cyber premiums at about $15.6 billion in 2025, rising to roughly $16.4 billion in 2026, and has cut its growth projection to a 5% compound annual rate with rates falling for a fourth year. Munich Re still sees around $28 billion by 2030.
Insured losses from natural catastrophes reached $107 billion in 2025, according to Swiss Re Institute. That is the sixth consecutive year above $100 billion, which is the part worth sitting with: the threshold is no longer an exception to plan around.
What changed in 2025 was which perils did the damage. The Los Angeles wildfires caused $40 billion of insured loss, the largest wildfire event on Swiss Re’s records, and severe convective storms added $51 billion worldwide. Wildfires, storms and floods together accounted for a record 92% of global insured losses, with hurricanes contributing comparatively little.
Swiss Re expects insured losses to reach $186 billion by 2030 if the long-run 5% to 7% annual real growth holds. That makes climate resilience a pricing and capacity question rather than a reporting one. Our follow-up on what the 2026 climate reports mean for insurance goes further into the numbers.
To encourage policyholders to take proactive steps to mitigate risk and minimize potential losses, insurers are offering discounts or premium reductions for climate-resilient upgrades.
Homeowners who invested in such upgrades - encouraged by their insurers - experienced significantly less damage compared to those who hadn't. Insurers who incentivized these measures saw fewer claims and reduced losses, demonstrating the effectiveness of climate adaptation incentives.
Last but certainly not least, let's talk about proactive risk management through predictive analytics.
This emerging trend in the insurance industry allows carriers to anticipate and mitigate risks before they occur. By applying advanced data analytics and machine learning models, your company can shift from a reactive approach - where claims are managed after an incident - to a proactive strategy focused on prevention.
How does this approach work in practice?
For instance, insurers can use predictive models to assess the likelihood of natural disasters, identify customers at higher health risks, or anticipate potential fraudulent activities.
By understanding these risks in advance, you can take steps to minimize losses, such as issuing early warnings to policyholders, recommending preventive actions, or adjusting underwriting criteria.
As the insurance industry evolves, it is essential to stay ahead of the curve by adapting to new trends and technologies. Here are some expert tips on how your insurance business can prepare for the future:
How Openkoda, a highly customizable PAS with 12 ready modules, compares with Guidewire PolicyCenter on configuration, AI, deployment and ownership.
A breakdown of the leading insurtech platforms in 2026, from core systems like Guidewire and Duck Creek to Openkoda, Socotra, Foliume, and HealthEdge.
Most of a bespoke insurance brief is standard policy administration. Scope the 80/20 split, start from a configurable PAS, and build only the rest.
Book a live, personalized demo with our product team - tell us your use case and see the platform work with your data. No commitment.