9 Best Insurtech Platforms in 2026
A breakdown of the leading insurtech platforms in 2026, from core systems like Guidewire and Duck Creek to Openkoda, Socotra, Foliume, and HealthEdge.
Seven insurtech trends for 2026, from embedded distribution and AI assistants to customizable PAS, self-service, legacy modernization and emerging risks.

Insurance technology is becoming more closely connected to everyday business decisions: which risks to accept, how to distribute products, where servicing costs accumulate, and how quickly teams can introduce changes.
Investment remains substantial. Gallagher Re reported $2.44 billion in global insurtech funding in Q2 2026, the highest quarterly total since Q2 2022. Large rounds accounted for much of that activity, which makes the headline figure a signal of concentrated investment rather than uniform growth across the market. Gallagher Re’s Q2 2026 report.
For insurers and MGAs, the practical question is where technology can improve performance. Faster product configuration, more useful AI, better distribution partnerships, and connected customer journeys all offer opportunities.
These seven insurtech trends show where those opportunities are developing, and what it takes to make them commercially useful.
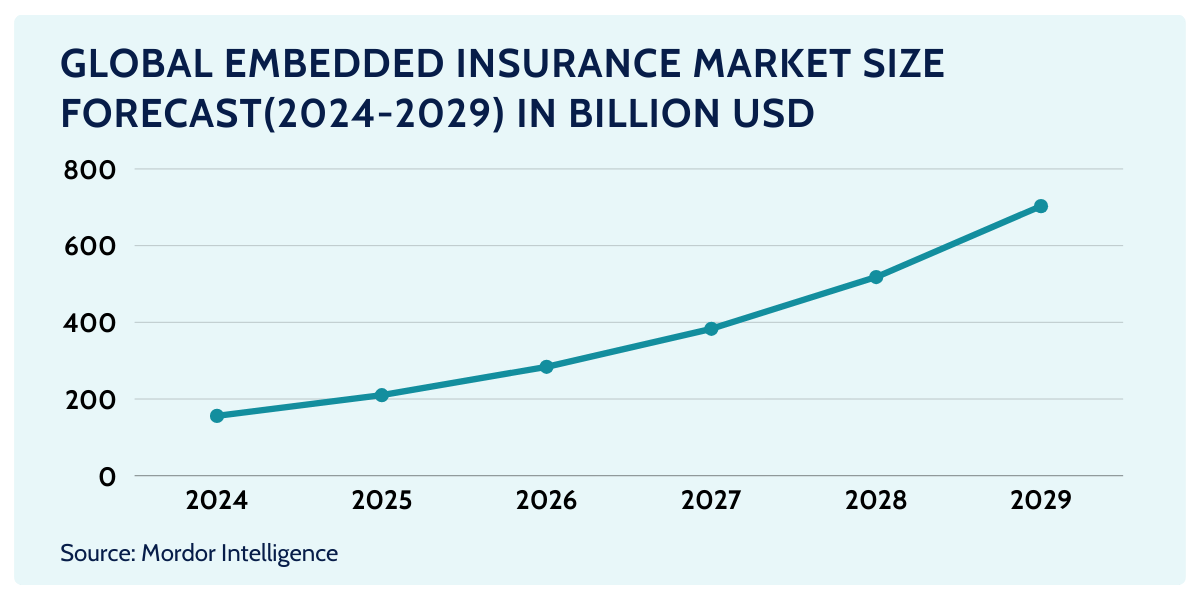
Embedded insurance is becoming an established distribution capability across travel, retail, financial services, mobility, and other commercial ecosystems.
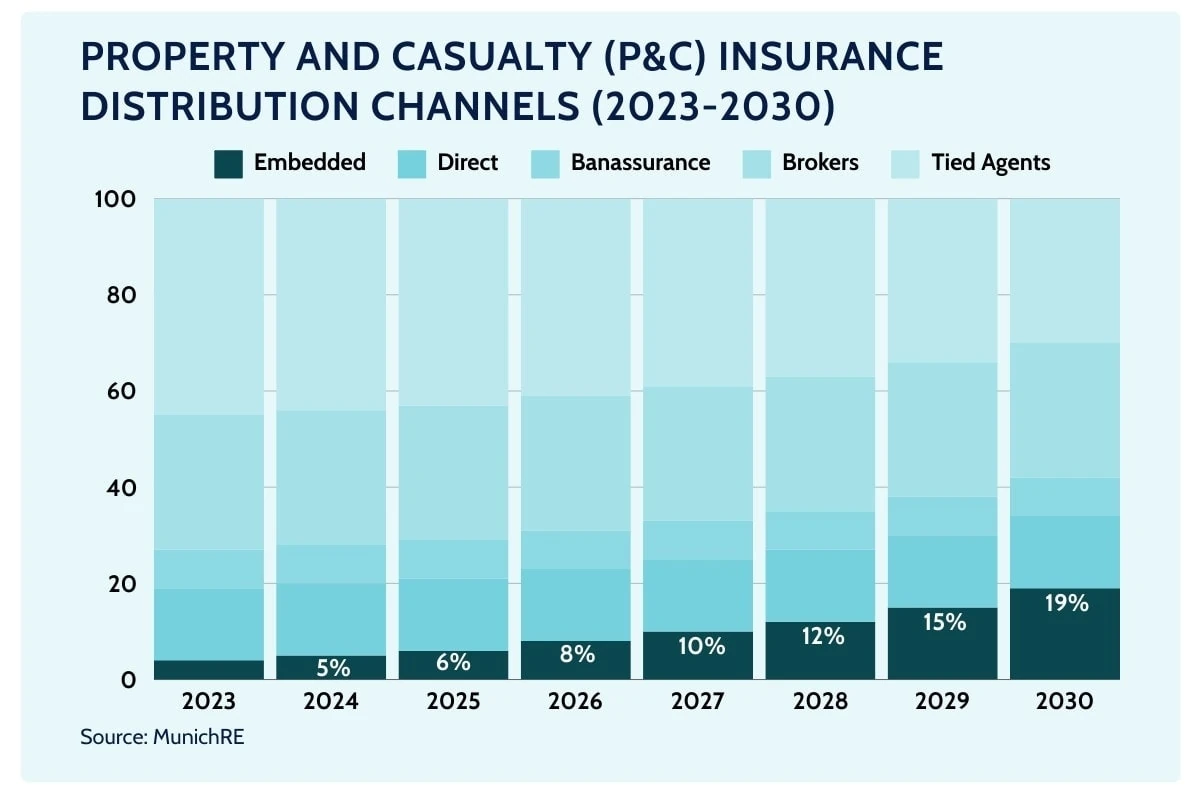
Its scale is visible in insurers’ own operations. In its 2025 shareholder letter, Chubb reported that Chubb Studio connected it with more than 250 digital partners, supporting insurance distribution within partners’ customer experiences. Chubb’s 2025 shareholder letter.
The opportunity extends across the customer relationship. Insurance can become relevant when someone books a trip, finances equipment, arranges a shipment, or subscribes to a service. Those interactions provide context that can help insurers present appropriate protection and reduce repetitive questions.
Cover Genius and Gather’s 2026 research surveyed 1,392 consumers across seven countries. Among respondents:
These findings measure stated preferences among surveyed consumers. They point to two design priorities: making protection understandable, and making benefits easier to access. 2026 Embedded Protection Report findings.
A strong embedded proposition needs to work after the initial transaction.
For a travel partnership, changing a booking may require amended cover. For equipment rental, extending the hire period may affect the insurance duration and premium. A cancelled purchase may require cancellation and reconciliation across several parties.
Insurers and distribution partners should therefore establish:
Openkoda’s Forms & Distribution capabilities let insurers configure branded applications and embedded insurance journeys around their product definitions. Its Enterprise offering adds partner submission APIs and insurance integrations alongside client and broker portals, connecting distribution with policy servicing.
The commercial advantage comes from keeping the offer, the issued policy, and subsequent transactions consistent as the partnership grows.
AI adoption is broadening, although implementation maturity varies considerably.
EIOPA’s February 2026 report, based on responses from 347 insurers across 25 countries, found that nearly two-thirds were actively using generative AI. Most remained at the proof-of-concept stage, which shows how much work still sits between experimentation and routine operational use. EIOPA’s generative AI survey.
Useful AI needs access to relevant records and a defined place in the workflow. Answering a product question, investigating portfolio performance, and changing an underwriting rule require different capabilities and different controls.
Openkoda illustrates this through Reporting AI, AI Product Builder, and its MCP server.
Openkoda Reporting AI lets users describe the information they need without writing a database query. It generates and executes the query, returns the report, and displays the query used to produce the result.
For example, a distribution manager could ask:
Show quote-to-bind conversion for our commercial property product by broker over the last quarter.
Using the records already in the PAS, the report can help identify where to investigate further. A lower conversion rate might prompt a review of referral turnaround, pricing, or the types of risk a broker submits.
Teams can save reports, export results to Excel, and build dashboards for underwriting, sales, finance, and operations. Queries are scoped to the organization’s data.
Openkoda’s AI Product Builder translates plain-language requirements into proposed changes to product configuration: coverages, limits, deductibles, pricing formulas, underwriting rules, and workflows.
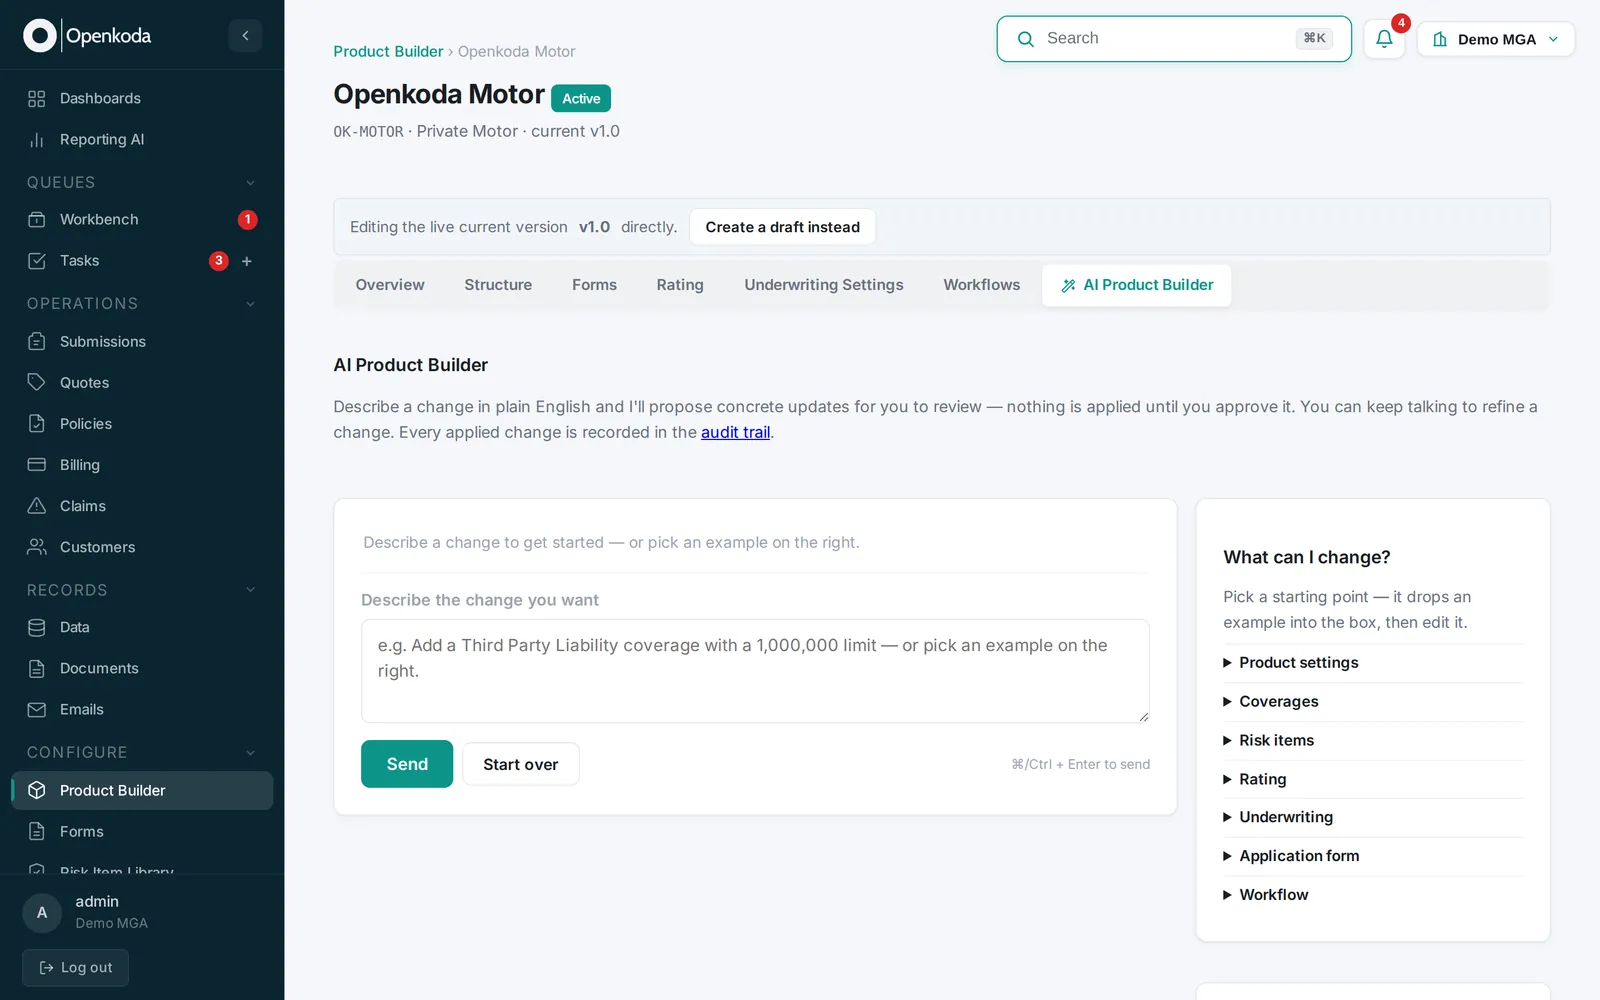
An illustrative instruction might be:
Add optional equipment breakdown cover to our commercial property product, with a £25,000 limit and £500 deductible. Refer requests for higher limits to an underwriter.
The team can inspect the proposed changes, refine the configuration, and complete the necessary product checks before approving publication.
Product versioning preserves the terms under which existing policies were issued. That matters when an insurer introduces new options or changes its underwriting approach while continuing to service an established book.
Openkoda’s MCP server for insurance connects compatible AI assistants, such as Claude Desktop, to the PAS through the Model Context Protocol.
Staff can use the assistant to query policies, claims, billing, and reports, then prepare operational actions.
Find policies renewing within 45 days that have open claims, then prepare a renewal draft for the account I select.
Other supported tasks include reviewing underwriting referrals, preparing a first notice of loss, and identifying overdue invoices for follow-up.
The connection uses the staff member’s own permissions. Changes are previewed and require explicit confirmation, and requests are recorded in the audit trail. Administrators can also restrict the connection to read-only access.
That makes conversational interaction useful for work spanning several records and screens. The MCP server is included with Openkoda Enterprise, while Reporting AI and AI Product Builder use the separate Openkoda AI subscription. Openkoda plans and pricing.
The ability to change insurance software has a direct effect on product strategy.
A specialist MGA may need unusual risk questions and referral rules. A carrier may want different renewal processes for separate customer segments. A distribution partnership may require a tailored application journey while using the same underlying product.
These requirements make customization relevant throughout the life of a system. The value becomes particularly visible after launch, when real submissions, claims, and servicing requests reveal what needs to change. It is also where vendor lock-in starts to bite, because the cost of a change is set by whoever controls the configuration.
Openkoda is a complete, highly customizable policy administration system. Insurers, MGAs, and insurtech businesses configure its insurance functionality around their products, underwriting approach, and operational responsibilities.
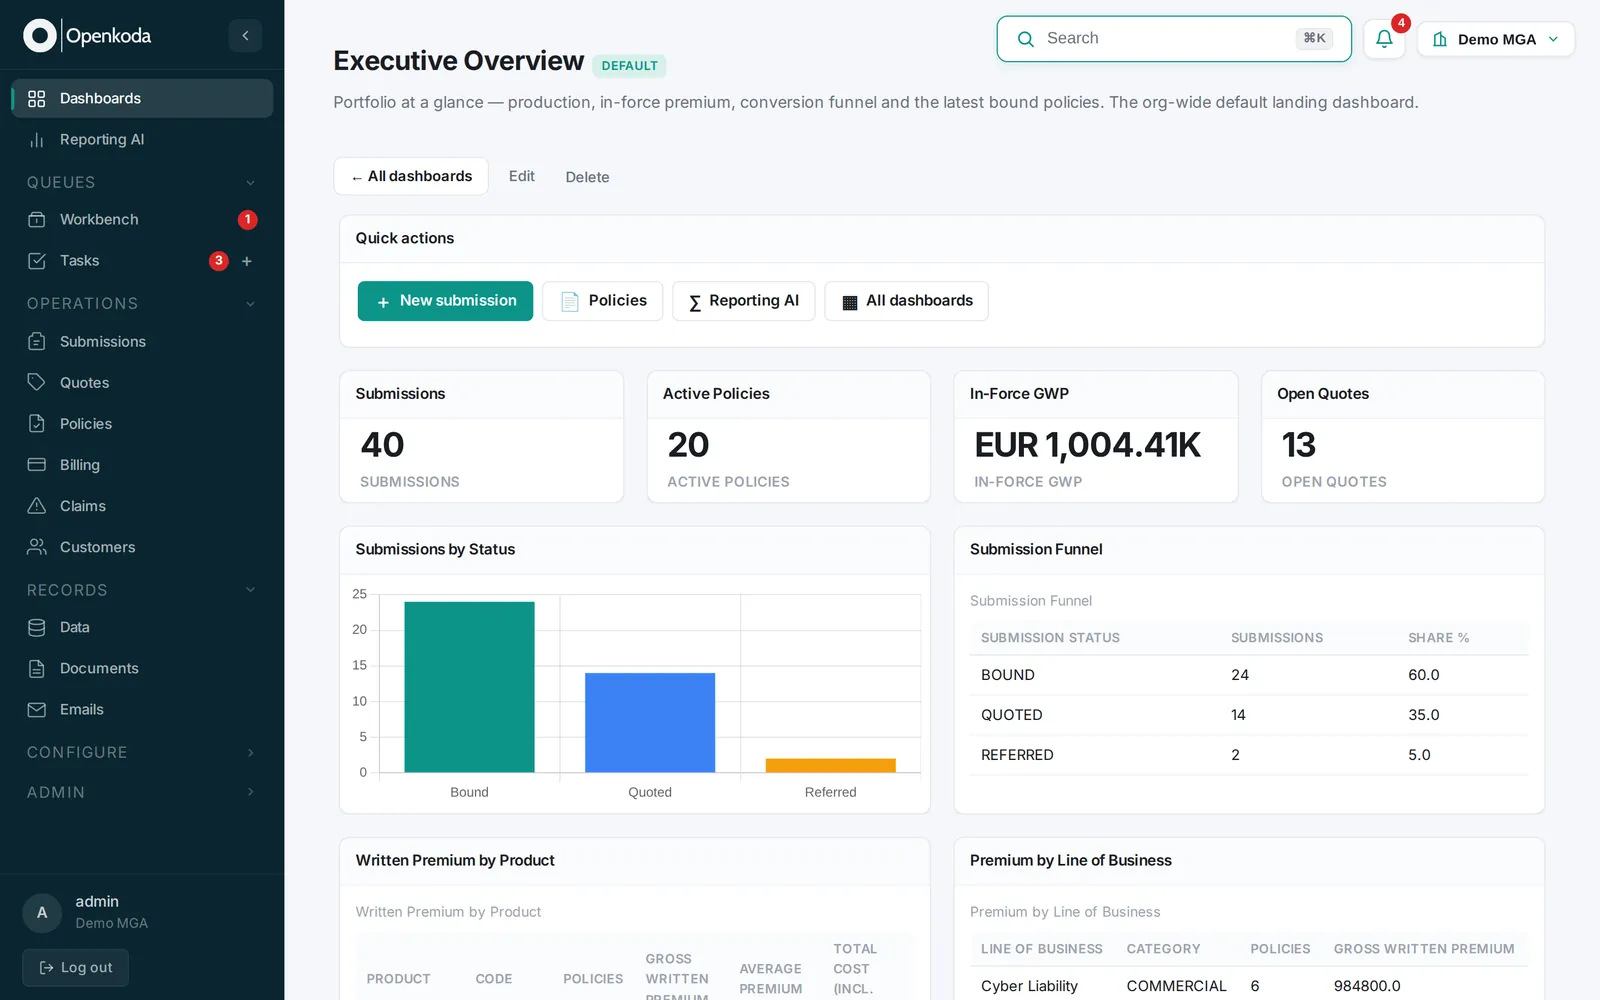
Its connected modules include:
These capabilities operate within the same PAS, which gives teams a connected starting point for customization. See the full Openkoda feature set.
Consider an MGA launching a commercial property scheme. It might need to capture multiple locations, offer optional equipment coverage, apply different deductibles, and refer selected occupations for underwriting review.
The team can configure those requirements across the application, pricing rules, referral process, and policy documents. Later it can introduce a revised product version while preserving the configuration attached to existing policies.
A second example is renewal servicing. An insurer could define a process that requests updated information, creates an underwriting task when specified conditions are met, generates an offer, and follows up on a schedule. The visual workflow automation engine supports simulation before activation and retains the original workflow version for cases already underway.
Openkoda supports managed cloud and on-premise deployment, with exportable data and configuration. Its team can provide additional customization and integrations where an implementation requires them.
For buyers, a useful evaluation is to demonstrate the second or third product change during selection. Adding an extension, revising a referral rule, or introducing another distribution channel will reveal how much control the business will really have after implementation.
Digital access is widespread, but the quality of the experience remains uneven.
J.D. Power’s 2026 U.S. Insurance Digital Experience Study found that satisfaction with insurers’ digital servicing fell four points to 695 on a 1,000-point scale. The study covered 11,553 evaluations and examined both shopping and servicing journeys. J.D. Power’s 2026 findings.
The practical opportunity is to make common tasks easier to complete:
A portal becomes more useful when it reflects the actual status of work inside the insurer. An acknowledgement that a request was received provides limited reassurance if the customer cannot see what happens next.
Measure completion rates, abandoned journeys, repeated contacts, and unresolved requests. Those show where self-service is helping customers and where a person is still needed.
Legacy modernization remains closely tied to product flexibility, data access, and the cost of change.
AI is beginning to affect the modernization process itself. McKinsey’s April 2026 analysis describes opportunities to recover knowledge from legacy systems, support testing, and improve reconciliation and cutover planning through AI-assisted work. McKinsey’s analysis of AI and insurance modernization.
A practical plan can follow several routes:
The choice depends on the condition of the existing estate and the business outcome required.
The most useful measures are operational: how quickly a product can change, how much manual reconciliation remains, whether staff trust the records, and how much effort a transaction takes. Those keep software modernization focused on improvements the business can verify.
Usage-based insurance continues to create opportunities for products that reflect how an insured asset is actually used.
Motor insurance provides an established example. Progressive’s Snapshot considers driving information such as mileage, time of day, and braking behavior. Its personalized pricing is reflected at renewal, which illustrates the distinction between collecting information continuously and applying a pricing change. How Progressive Snapshot works.
Product teams need to define the relationship between incoming data and the insurance contract:
Connected claims create another use for timely data. A crash alert could prompt a customer to begin a claim, while a leak notification could initiate assistance and evidence collection.
The value depends on connecting the event to the correct policy, insured asset, and workflow. Reliable timestamps, clear data provenance, and well-defined exception handling are what make these services usable day to day.
Climate exposure, cyber dependencies, and AI infrastructure are creating demand for more detailed underwriting information and specialized coverage.
Swiss Re Institute estimated $42 billion in global insured natural catastrophe losses in the first half of 2026, against approximately $100 billion in economic losses. Insured losses were below the long-term trend, but the institute highlighted continuing pressure from growing exposure, rising asset values, and changing hazards. Swiss Re’s first-half 2026 analysis.
For product teams, that reinforces the importance of location-level information, exposure monitoring, and practical risk-reduction measures. Parametric products can also address defined needs where reliable event measurements and appropriate payout structures are available.
Cyber underwriting increasingly requires a clear view of operational dependencies. Shared technology providers, outsourced services, and critical systems can connect exposures across an otherwise diverse portfolio.
AI infrastructure adds another area for specialist underwriting. Gallagher Re’s Q2 2026 report examines the insurance implications of data-center expansion, including the scale, complexity, and cost of the facilities and equipment involved. Gallagher Re’s analysis.
Useful capabilities for these products include capturing detailed asset and dependency information, monitoring concentrations across locations and counterparties, recording changing underwriting assumptions and product versions, connecting specialist claims expertise to the relevant coverage, and updating questions, referral rules, and reporting as experience develops.
Those requirements are what make adaptable software valuable to specialist insurers and MGAs, rather than adaptability as a virtue in itself.
The strongest insurtech opportunities in 2026 connect a business problem with a measurable improvement: a clearer purchase journey, a faster product change, a better-informed underwriting decision, or a simpler service request. Choose technology that supports those outcomes and leaves room to improve the process as the team learns.
A breakdown of the leading insurtech platforms in 2026, from core systems like Guidewire and Duck Creek to Openkoda, Socotra, Foliume, and HealthEdge.
Where insurers can innovate in 2026: embedded insurance, custom claims and policy apps, AI analytics, personalized products and specialty lines.
Five trends shaping insurance in 2026, from embedded cover and AI at scale to niche products, climate resilience and predictive risk management.
Book a live, personalized demo with our product team - tell us your use case and see the platform work with your data. No commitment.