P&C Insurance Billing Software: 9 Systems Compared for 2026
Billing is where a missed installment turns into a cancellation notice with a legal deadline. Nine P&C billing systems compared on bill types, delivery and pricing.
What legacy systems actually cost an insurer, and a five-step route to a configurable PAS that moves one scope at a time while the book keeps running.

A legacy insurance system can process today’s book reliably while making tomorrow’s business increasingly difficult to support. The pressure shows up in everyday work: a pricing adjustment that requires a development release, an endorsement handled across several applications, or a renewal report assembled by hand from separate databases.
Those limitations affect more than IT expenditure. They decide how quickly an insurer can respond to changing risk, support its distribution partners, and bring new products to market.
Modern policy administration systems give insurers more practical options. Configurable products, automated workflows, connected records, and AI-assisted tools make it possible to improve operations while giving business teams greater control over change.
For established insurers, the question is how to make that transition while preserving policy history, financial accuracy, and continuity of service. A phased approach can introduce new capabilities while existing business keeps running.
The starting point should be a measurable business objective: shorten the time needed to change a product, reduce manual underwriting handoffs, improve renewal processing, or retire expensive duplicate systems. Those priorities decide what moves first and how success is measured.
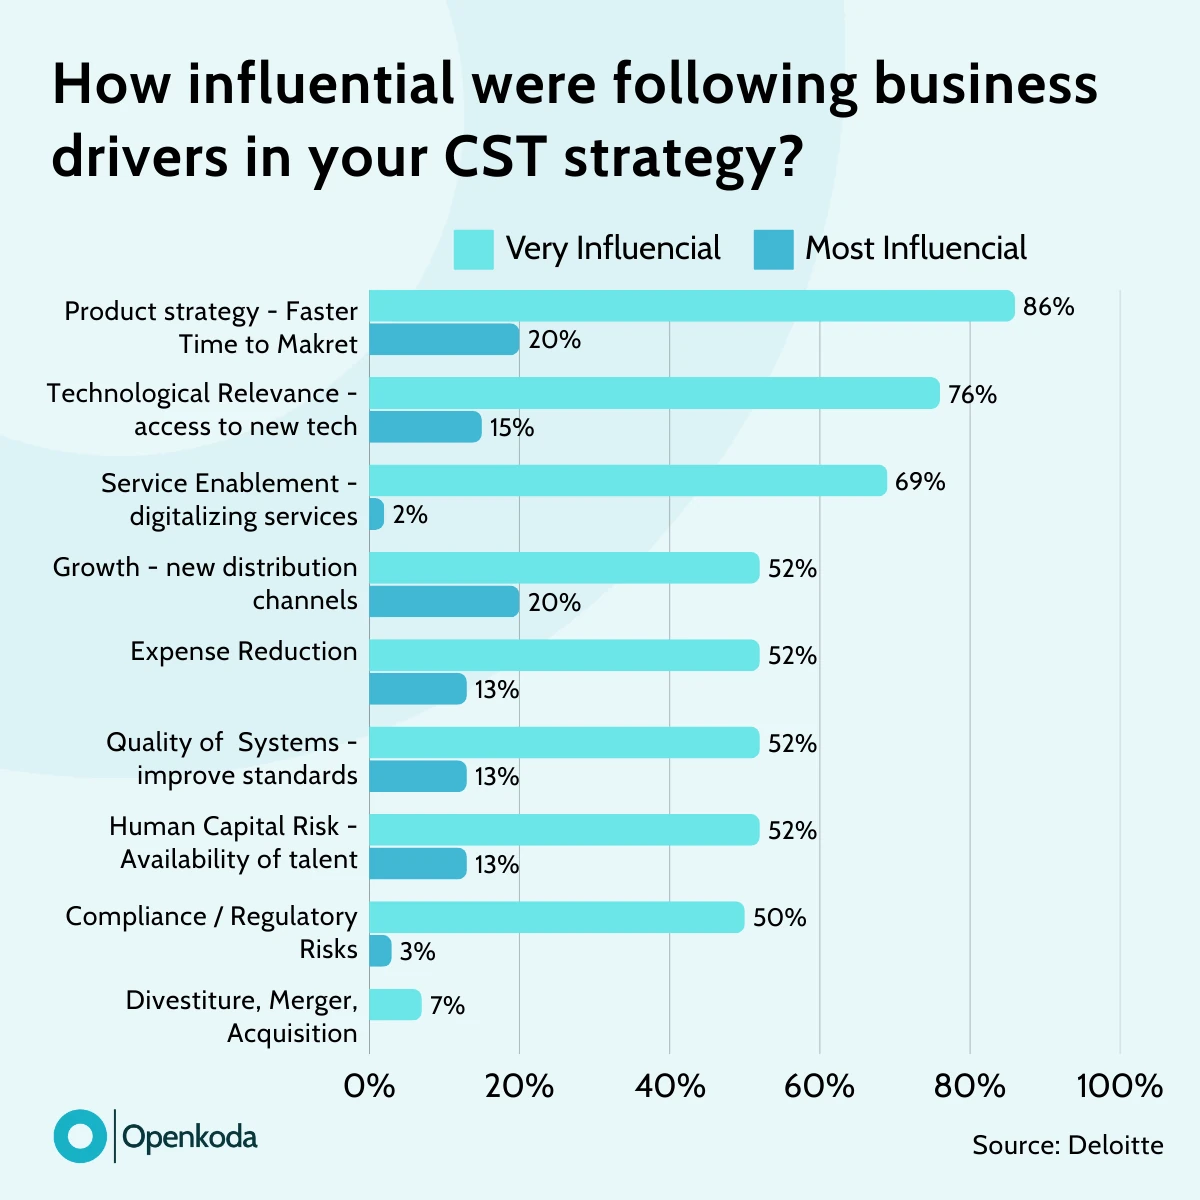
Apart from looking into the future, one of the key drivers for insurance industry to modernize its software foundation is the fact that it can no longer support ongoing operations. Even though many companies still believe in the "if it ain't broke don't fix it approach" legacy systems often cause significant cost and operational overruns forcing the management to invest in modernization sooner or later.
Legacy insurance software increases the cost of policy management and customer acquisition because it requires frequent and costly maintenance, relies heavily on manual processes, struggles with integrating modern technologies, and offers a poor customer experience. These factors result in inefficiencies, higher operational expenses, and more resources spent acquiring and retaining customers.
Just how big of a problem is it?
According to the latest data, insurers allocate roughly 70% of their IT budgets solely to maintaining outdated systems, leading to escalating policy management and customer acquisition costs.
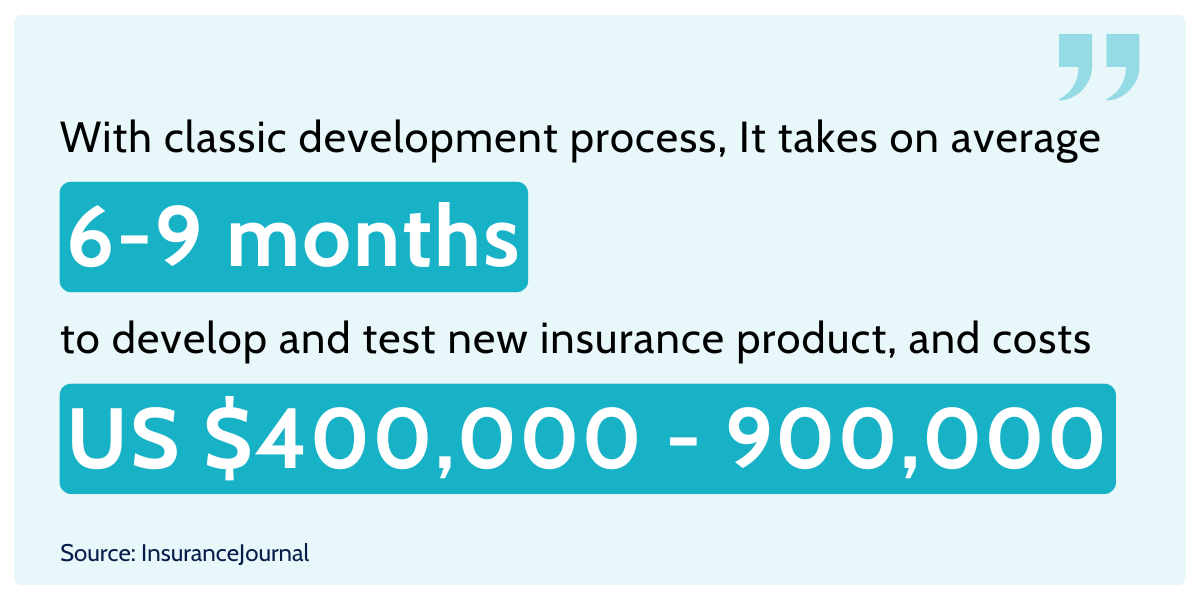
Insurance firms launching new products encounter significant delays due to manual configurations across interconnected legacy systems. The average development cycle extends 6-9 months, costing US$400,000–900,000 per product, severely constraining innovation and market responsiveness.
But increased cost isn't all.
When insurance companies want to update or modify premium calculation logic, adjust pricing strategies, or introduce new product features, these legacy systems often require complex, manual coding efforts. Since older systems weren't designed for quick or easy adjustments, even small changes can necessitate lengthy development cycles, extensive testing, and specialized technical expertise.
Legacy systems, often built on proprietary technology, face severe integration limitations, hindering clean connections with digital ecosystems. Due to their outdated architectures, these older platforms frequently lack modern APIs or standardized interfaces, making integration with newer tools - such as CRM platforms, automation software, or third-party data providers - difficult or even impossible.
As a result, insurers may encounter significant technical challenges, requiring custom-built integrations that are costly, complex, and fragile.
We've discussed the technical limitations of legacy systems within the insurance industry. To craft a winning strategy for insurance legacy system transformation we must also explore four key areas of insurance operations where outdated systems might really hinder the operational efficiency.
These are the key areas in which upgrading your outdated system can improve the business efficiency in the most profound way.
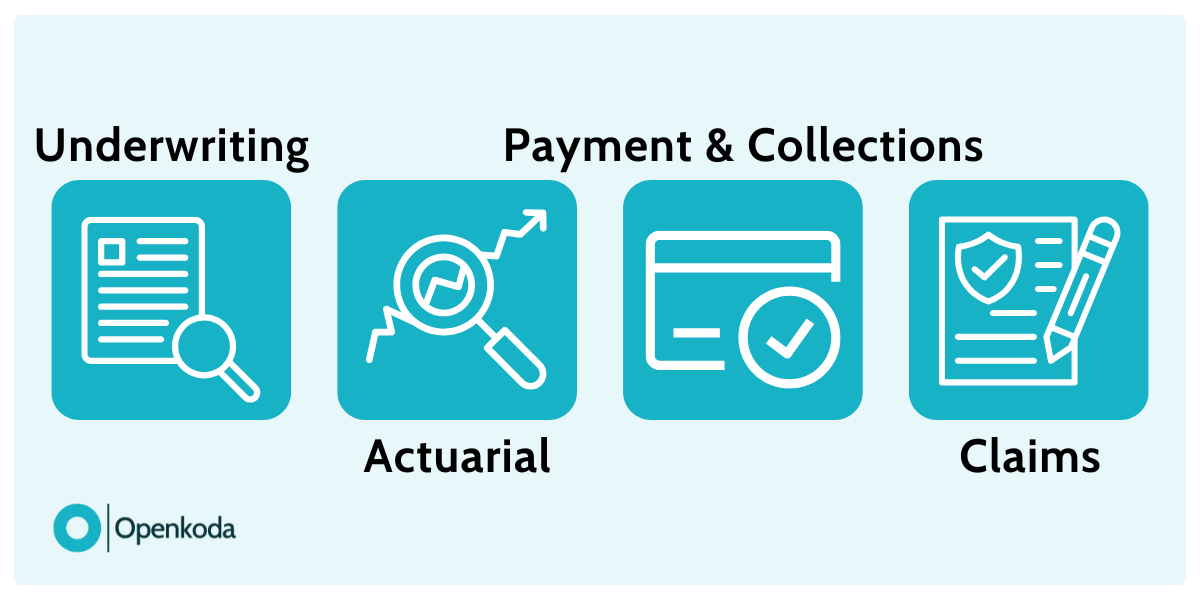
Legacy underwriting platforms often suffer from fragmented data structures and limited automation capabilities. Underwriters working with outdated software typically face data silos, making it cumbersome to gather a holistic view of client risk profiles and history. This leads to inconsistent underwriting decisions, reduced speed, and missed opportunities for accurately segmenting risks.
For instance, when insurers attempt to integrate external data sources (IoT sensors, telematics, social media analytics) into older systems, they frequently encounter compatibility issues or manual workarounds that significantly delay underwriting cycles and degrade data integrity.
In actuarial operations, legacy systems make report preparation particularly cumbersome because actuaries must manually fetch, consolidate, and validate data from multiple, disconnected systems. This manual data handling process is not only time-consuming but also prone to errors or data omissions, directly affecting the accuracy and timeliness of critical financial or risk assessment reports.
Why is it so problematic? It's because such processes can be done in 1/10 of the time with modern systems especially with the usage of generative AI technology.
Openkoda reporting AI functionality, for example, accelerates report preparation by enabling users to generate SQL queries through natural language prompts, eliminating the need for technical SQL expertise. This functionality operates entirely within the system (only the database schema is shared with OpenAI API), ensuring that sensitive client data remains secure and is not shared externally.
Legacy insurance platforms commonly lack integration with modern payment solutions, complicating premium collection and reconciliation processes. With modern systems, insurers can just divert users to a dedicated section of their client portal with an integrated Stripe payment gateway and streamline the whole process for improved customer satisfaction.
In complex legacy systems without automated payment capabilities, staff may spend unnecessary amounts of time manually verifying payments, following up on missed transactions, and resolving discrepancies.
Legacy claims processing systems typically lack flexibility, automation, and advanced decision-support mechanisms needed for modern insurance operations. Insurers using these outdated solutions frequently encounter bottlenecks stemming from manual reviews, paper-based workflows, and isolated document generation systems.
For instance, outdated claims systems often provide limited or no integration with advanced fraud detection technologies, predictive analytics, or intelligent triage engines. As a result, claims handlers are burdened with repetitive tasks, reducing productivity and significantly increasing cycle times.
The takeaway is simple: in claims processing systems, flexibility is key. Upgrading to modern claims processing technology allows insurers to deliver enhanced customer service, maintain operational efficiency, and gain a competitive advantage.
While applying the core principles of Extend, Modernize, and Replace, is key for strategic planning, insurance companies must also navigate several common challenges. Understanding these hurdles early in the process allows insurers to effectively plan, mitigate risks, and ensure smooth transitions.
Below are the most frequent challenges insurance companies face during legacy system modernization, along with insights on managing and overcoming them successfully:
Modernizing insurance software starts with deciding which capabilities your business needs and how they should work together.
If your existing stack handles policy administration, underwriting, billing, documents, and reporting through a collection of aging applications and custom workarounds, a configurable PAS offers a practical route forward.
Openkoda is a mature, highly customizable policy administration system with ready insurance modules. Its existing functionality is the starting point for a modernization project, with configuration and custom development used to accommodate your products, integrations, and specialist workflows.
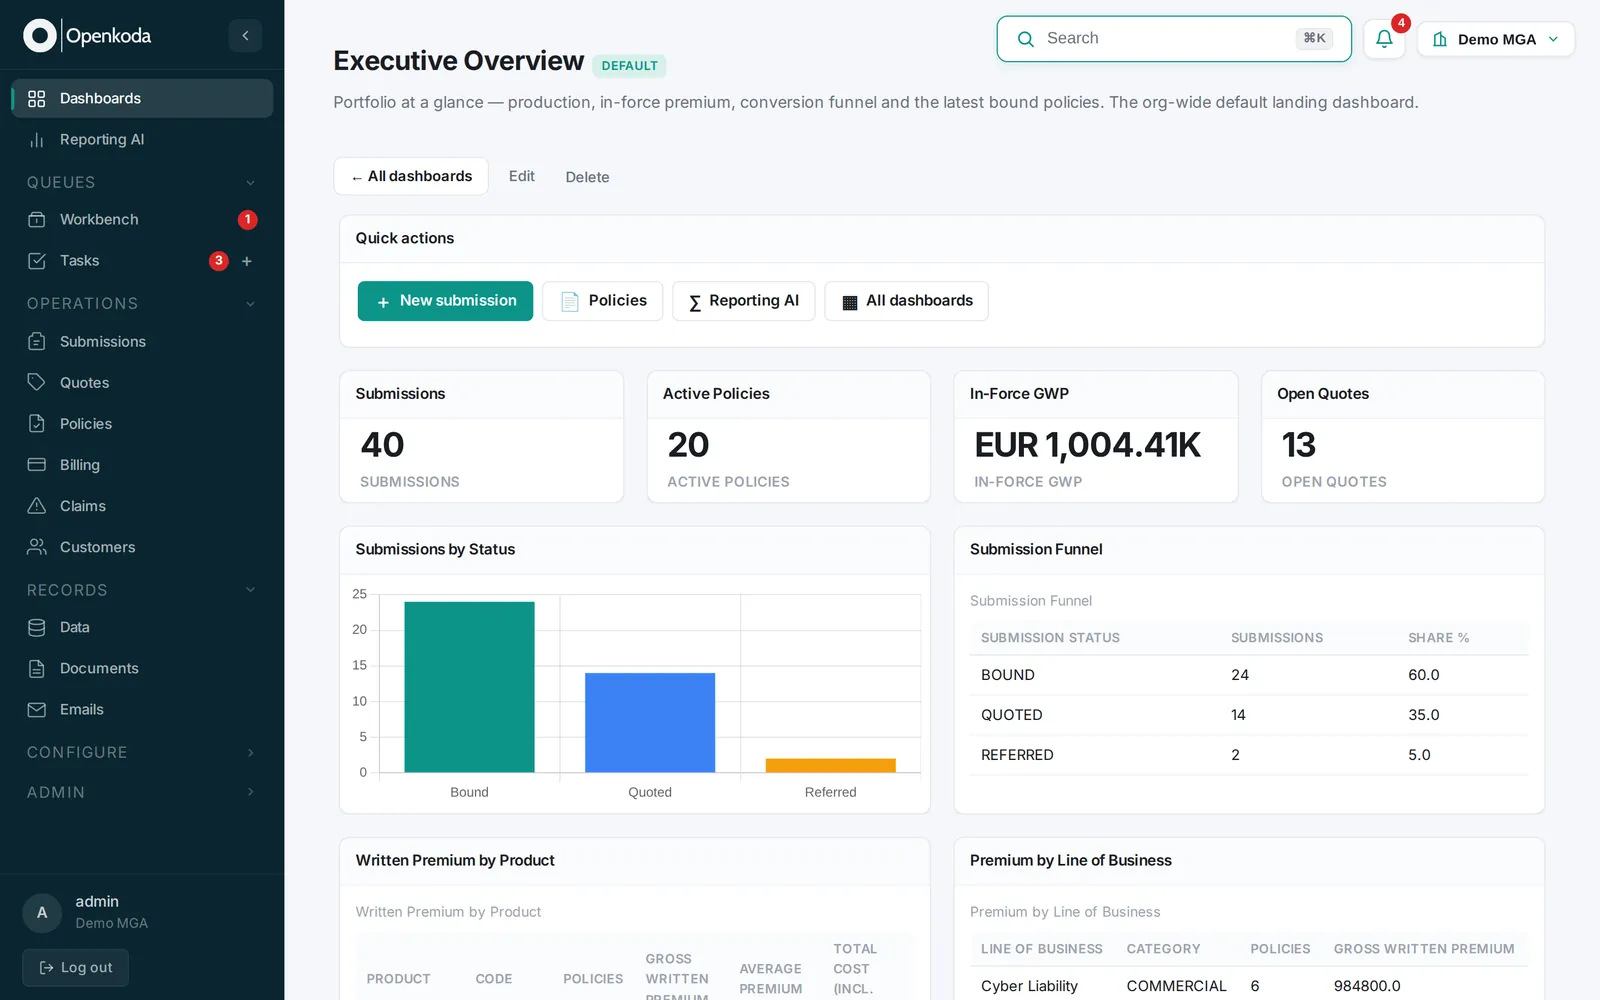
Openkoda also supports phased modernization: introducing a product or line of business on the new PAS, connecting it to the existing environment, and progressively moving the operation across.
The process combines insurance expertise, configuration, integration, and migration planning. The Openkoda team of insurance technology professionals works with your business to define the scope, and provides custom development services where deeper extensions are required.
Map the systems, data, and manual processes supporting the book. Identify where information is duplicated, which integrations remain essential, and which workarounds exist only because of limitations in the current software.
Then select a manageable first scope: a new product, one line of business, or a defined portfolio.
Agree the success measures before implementation begins. Referral turnaround time, manual steps per endorsement, or the time required to prepare renewal offers are all reasonable candidates.
Model coverages, pricing, underwriting rules, documents, approval paths, and user roles in Openkoda. Review what the ready modules support and identify any requirement needing custom development.
This is also an opportunity to simplify. A manual approval introduced years ago to compensate for missing data may no longer be necessary once that information is available inside the workflow.
Underwriters, servicing staff, and finance teams should review working examples early, using representative cases from the business.
Decide which policies, customers, claims, documents, balances, and historical records need to move, and which can stay accessible through an archive or the existing system.
Data preparation has to preserve business meaning as well as field values. Effective dates, coverage terms, transaction relationships, and outstanding balances need to remain understandable and reconcilable after migration.
For some portfolios, launching new business on Openkoda while existing policies stay on the legacy system is the most practical first step. Other books suit migration at renewal, or in defined batches.
Scope the connections required for systems that remain in use: accounting, CRM, payment services, external rating tools, and carrier reporting.
Openkoda provides REST APIs, webhooks and deployment options, while connections to particular legacy systems may need adapters or other integration work.
Testing should follow complete insurance transactions. Process a submission, referral, endorsement, cancellation, and renewal; check the resulting premiums, documents, balances, and reports. Where old and new systems coexist, define which system owns each transaction and how discrepancies get resolved.
Train the first user group, launch the agreed scope, and watch the operational results. Use what you find to refine the configuration before extending the rollout.
Retire legacy components once their processing responsibilities have moved and the required historical information stays accessible. Put ownership, support arrangements, and recovery procedures in the transition plan.
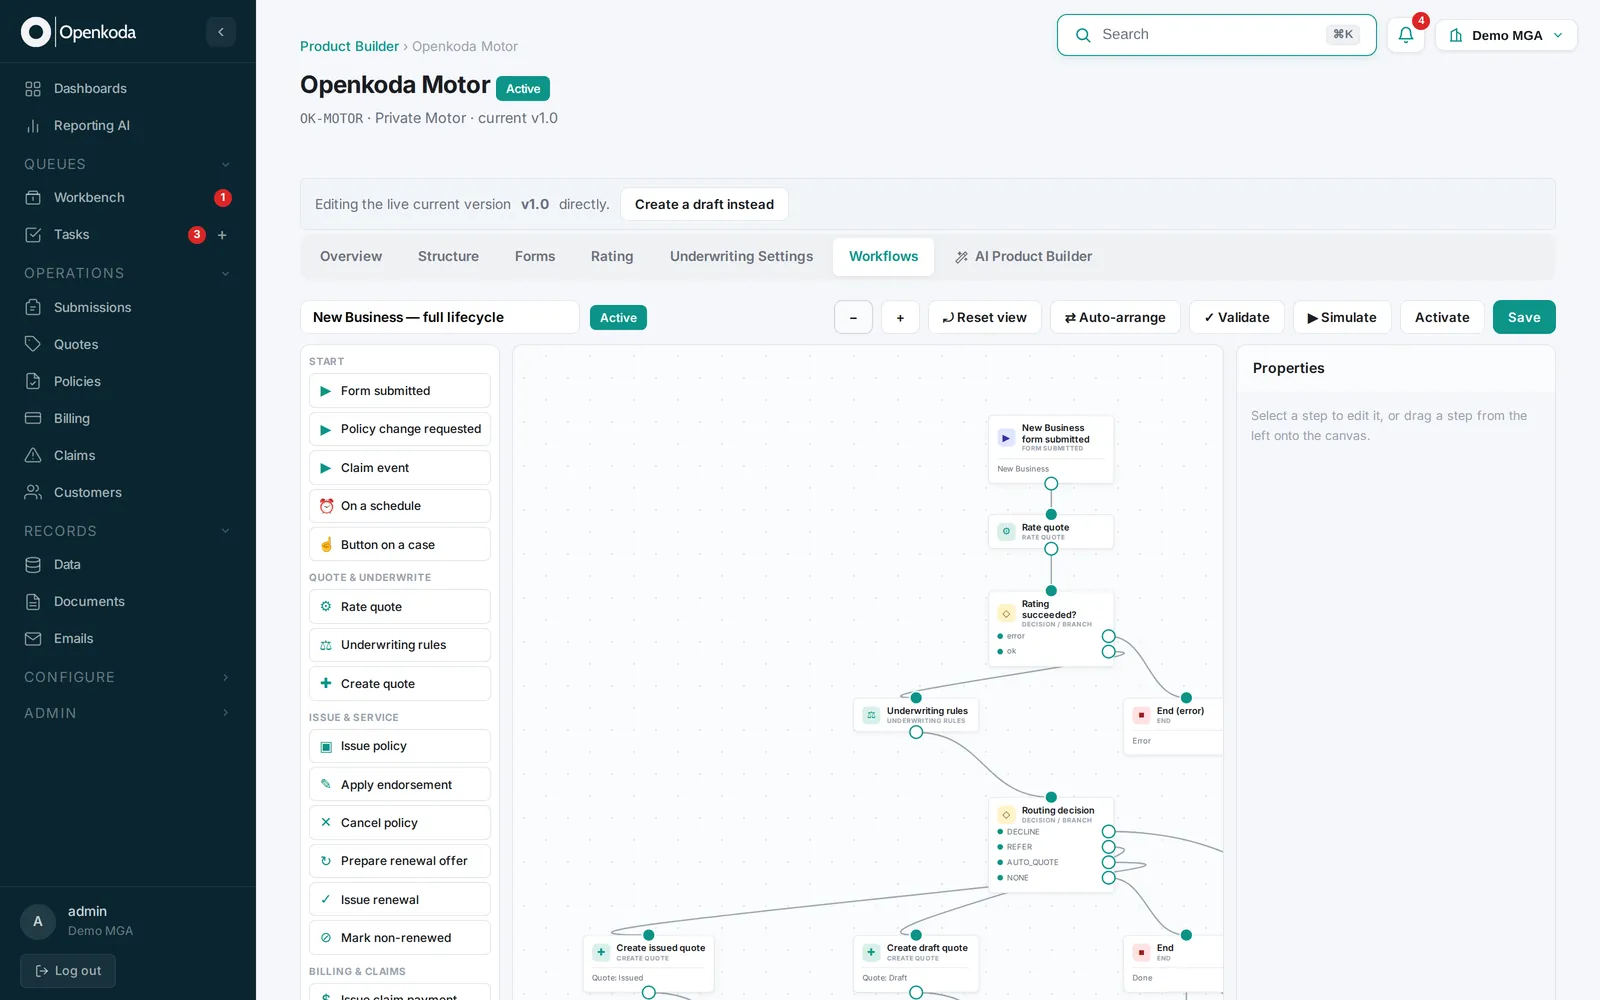
A focused first deployment can target around three weeks, with scope agreed upfront. Migrating an established book has its own timetable, shaped by data quality, integrations, product complexity, and validation requirements.
Openkoda already provides the insurance functionality needed to support the move. The capabilities that matter most to a modernization project:
The implementation scope should identify which modules, integrations, and subscription options the business needs. AI features use a separate subscription, and capabilities such as portals and multi-organization support depend on the selected Openkoda plan and pricing.
Successful modernization should leave the business with fewer manual dependencies and a system it can keep adapting. Start with a clear operational objective, prove the new processes on a manageable scope, and expand as the results justify it.
Billing is where a missed installment turns into a cancellation notice with a legal deadline. Nine P&C billing systems compared on bill types, delivery and pricing.
A policy administration system decides how fast business changes reach the policies you write. Key 2026 features, a buyer's checklist and 10 systems compared.
MGA policy administration software has to handle binders, referrals, bordereaux and commission for every capacity provider. What to look for, and 10 systems compared.
Book a live, personalized demo with our product team - tell us your use case and see the platform work with your data. No commitment.